Buying a house is one of the biggest financial decisions many people make in their lifetime. For some, owning a home represents security, stability, and success. For others, investing money in mutual funds offers a flexible way to build wealth without committing a large amount of money to a single asset.
But what happens when you have enough savings to choose between buying a house and investing in mutual funds? Which option could help you build more wealth over the next 10, 15, or 20 years?
The answer depends on your financial goals, income, existing savings, family responsibilities, risk tolerance, and investment timeline. A house can provide a place to live and may appreciate in value, while mutual funds can offer diversification, flexibility, and the potential for long-term growth. However, both options involve costs and risks.
In this guide, we will compare buying a house and investing in mutual funds in India, examine a practical financial example, and explain how to decide which option may suit your situation.
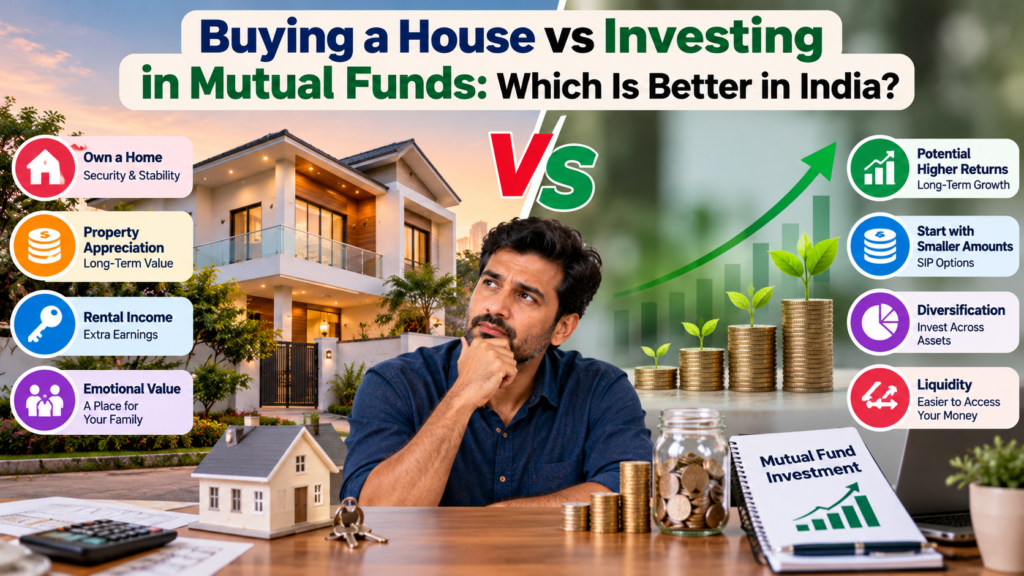
Buying a House vs Investing in Mutual Funds: Quick Comparison
| Factor | Buying a house | Investing in mutual funds |
|---|---|---|
| Initial investment | Usually high | Can start with relatively small amounts |
| Potential returns | Property appreciation and possible rental income | Returns depend on the type of fund and market performance |
| Monthly commitment | Home loan EMI, if financed, plus maintenance | Optional SIP contributions based on your plan |
| Liquidity | Generally low; selling can take time | Often higher for open-ended funds, subject to scheme rules |
| Diversification | Large amount may be concentrated in one property | Can spread money across multiple securities |
| Additional costs | Registration, stamp duty, maintenance, repairs and other charges | Fund expenses, applicable transaction costs and taxes |
| Emotional value | Can provide stability and a home for your family | Primarily a financial investment |
| Main risks | Property prices, location, legal issues, vacancies and debt | Market fluctuations, credit risk and other fund-specific risks |
| Regular income | Possible rental income | Depends on the investment and how returns are realised |
| Best suited for | People who need a home or understand property investing | People seeking flexible, market-linked investment options |
There is no universal winner. A home purchased for personal use serves a different purpose from an investment intended to grow your savings.
1. What Does Buying a House Mean as an Investment?
Buying a house involves purchasing residential property that you can live in, rent out, or potentially sell in the future.
Many Indian families prefer property because it is a physical asset. You can see it, use it, and potentially pass it on to your children. A home may also protect you from rising rental costs if you plan to live in it for many years.
However, owning a property is not automatically a profitable investment. The final financial outcome depends on the purchase price, location, construction quality, financing costs, maintenance expenses, rental income, and eventual selling price.
Advantages of buying a house
1. You get a place to live
If you purchase a house for your own use, you gain a place to live without depending on a landlord. This can provide stability, particularly if you expect to remain in the same city for a long time.
2. Potential property appreciation
A property in a desirable location may increase in value over time. Infrastructure development, employment opportunities, transport connectivity, and local demand can influence property prices.
However, appreciation is not guaranteed. Some properties may remain stagnant in value or lose value because of poor maintenance, oversupply, legal problems, or changing local conditions.
3. Possible rental income
If you purchase a property for investment, you may be able to rent it out. Rental income can help cover maintenance costs, property expenses, or part of a home loan EMI.
The actual benefit depends on the rent you receive, vacancy periods, repairs, taxes, and other expenses.
4. Long-term housing stability
Owning a home can reduce uncertainty about future rent increases and landlord decisions. For families with children or people who want to settle in one location, this may be an important non-financial benefit.
5. A tangible asset for your family
Some people value property as a long-term family asset. A home may be used by future generations or sold when financial needs change.
Disadvantages of buying a house
1. High upfront cost
Buying a property usually requires a down payment, stamp duty, registration fees, and other transaction expenses. Furnishing, repairs, and moving costs may add to the initial amount.
2. Home loan interest
If you borrow money to buy a house, the total cost includes interest paid over the loan term. A large EMI can reduce the money available for savings, investments, education, and emergencies.
3. Low liquidity
A house cannot usually be converted into cash as quickly as an investment in an open-ended mutual fund. Finding a buyer, completing legal checks, and transferring ownership can take time.
4. Maintenance and repair expenses
Property ownership comes with recurring costs, including repairs, painting, plumbing, electrical work, society charges, insurance where applicable, and property tax.
5. Concentration risk
A large portion of your wealth may be tied up in one property, one location, and one local property market. If that area performs poorly, your investment may suffer.
2. What Does Investing in Mutual Funds Mean?
A mutual fund pools money from multiple investors and invests it according to the scheme’s stated objectives. Depending on the fund, the portfolio may contain shares, bonds, money-market instruments, or a combination of assets.
For example, an equity mutual fund invests primarily in shares, while a debt mutual fund invests in debt-related instruments. Hybrid funds combine different asset classes according to their investment strategy.
Mutual funds allow people to invest without purchasing individual securities themselves. They also make it possible to invest gradually through a Systematic Investment Plan, commonly known as an SIP.
Advantages of investing in mutual funds
1. You can start with a smaller amount
Unlike property, mutual funds generally do not require a large down payment. Depending on the scheme, you may be able to begin with a relatively small investment.
This makes mutual funds accessible to people who are still building their savings.
2. Potential for long-term wealth creation
Equity mutual funds may provide long-term growth potential, although returns can fluctuate substantially. Debt and other types of mutual funds have different risk and return characteristics.
Your results depend on the type of fund, investment period, market conditions, expenses, and your behaviour during market fluctuations.
3. Greater flexibility
Many open-ended mutual funds allow investors to redeem units on business days, subject to the scheme’s terms, settlement rules, exit loads, and any applicable restrictions.
This generally makes them more flexible than selling a house. However, redeeming during a market downturn can mean receiving less than you invested.
4. Diversification
A mutual fund can hold securities from multiple companies, industries, or issuers. This can reduce the impact of a poor result from a single investment, although diversification does not eliminate market risk.
5. Convenient monthly investing
An SIP allows you to contribute a fixed amount at regular intervals. This can help make investing a consistent habit instead of waiting until you have accumulated a large sum.
6. Easier portfolio adjustments
You can review your investments and adjust your asset allocation as your goals, age, and financial circumstances change. The suitability of any change depends on your objectives and the tax and transaction consequences.
Disadvantages of investing in mutual funds
1. Market fluctuations
The value of mutual fund investments can rise or fall. Equity funds may experience significant declines during market corrections, economic uncertainty, or company-specific problems.
2. Returns are not guaranteed
Past performance does not guarantee future returns. A fund that performed well in previous years may deliver lower returns or losses in the future.
3. Emotional decision-making
Some investors panic when markets fall and sell their investments at an unfavourable time. Others take excessive risks after seeing short-term gains.
A suitable investment plan should account for your ability to tolerate losses and remain invested during difficult periods.
4. Expenses and taxes
Mutual funds charge expenses, and taxes may apply when you receive distributions or sell your investments at a gain. The details depend on the fund category, holding period, investor circumstances, and current tax rules.
5. No direct housing benefit
A mutual fund does not provide a place to live. If you invest instead of buying a home, you may still need to pay rent or purchase a property later.
3. Example: Buying a House Worth ₹50 Lakh vs Investing in Mutual Funds
Let’s compare two hypothetical choices to understand how the money might work.
Imagine you have ₹15 lakh available for a down payment or investment. You are considering a house worth ₹50 lakh and a home loan for the remaining amount, or investing the ₹15 lakh in mutual funds.
For illustration, assume the following:
- House purchase price: ₹50 lakh
- Down payment: ₹15 lakh
- Home loan: ₹35 lakh
- Illustrative loan interest rate: 8.5% per year
- Illustrative loan tenure: 20 years
- Alternative investment: ₹15 lakh invested in mutual funds
These are example figures, not current loan quotations or forecasts.
Option A: Buy the house
With a ₹35 lakh loan at an illustrative interest rate of 8.5% over 20 years, the EMI would be approximately ₹30,400 per month.
Over the full loan term, total EMI payments would be approximately ₹73 lakh, of which around ₹38 lakh would be interest, assuming the interest rate remains unchanged and the loan is repaid according to schedule.
This does not include the down payment, stamp duty, registration, maintenance, repairs, property tax, or other expenses.
You would own a house, but your finances would also be committed to a long-term repayment obligation.
Option B: Invest the ₹15 lakh in mutual funds
Suppose you invest ₹15 lakh as a lump sum in a mutual fund portfolio.
The final value would depend on the actual returns. To demonstrate the effect of different assumed annual growth rates, consider these hypothetical outcomes over 20 years:
| Assumed annual return | Illustrative value after 20 years |
|---|---|
| 6% | ₹48.1 lakh |
| 8% | ₹69.9 lakh |
| 10% | ₹100.9 lakh |
| 12% | ₹144.7 lakh |
These figures use annual compounding for illustration. They are not promised returns, and actual mutual fund performance will not follow a fixed annual rate. Fees, taxes, market volatility, and inflation affect the real outcome.
Also, this comparison is not yet an equal-cost comparison. The home buyer pays a monthly EMI, while the mutual fund investor in this example invests only the initial ₹15 lakh.
What if you invest the EMI amount instead?
A fairer comparison should also consider what happens to the money that would otherwise be paid toward the home loan.
If you rent a home and invest both the initial ₹15 lakh and an amount equivalent to the monthly EMI, your potential investment value could be higher. However, you must subtract rent, account for rent increases, and consider any differences in living costs.
Likewise, the homeowner builds equity through loan repayment and may benefit from property appreciation, but must account for maintenance, transaction costs, and the cost of financing.
The key lesson: Comparing the house’s future selling price directly with a mutual fund’s future value is not enough. You must compare the total cash flows, costs, housing benefits, and risks of both choices.
4. What If You Invest Through an SIP Instead of Buying a House?
An SIP can be useful for people who want to invest gradually instead of making a large property purchase.
For example, suppose you invest ₹10,000 per month for 20 years. The total amount contributed would be ₹24 lakh.
Using hypothetical monthly compounding assumptions, the potential future values could look approximately like this:
| Assumed annual return | Illustrative value after 20 years |
|---|---|
| 6% | ₹46 lakh |
| 8% | ₹59 lakh |
| 10% | ₹76 lakh |
| 12% | ₹99 lakh |
These are illustrations, not expected or guaranteed mutual fund returns. Actual results can be lower or higher, and market-linked investments can lose value.
An SIP does not guarantee profits or eliminate risk. Its main practical benefit is that it helps you invest regularly without needing to accumulate a large amount before starting.
If your goal is to buy a house in the near future, the appropriate investment may be different from one intended for retirement decades away. Money needed soon generally should not be exposed to more market risk than you can afford.
5. Property Appreciation vs Mutual Fund Returns
Property prices and mutual fund returns are influenced by different factors.
What affects property prices?
Property values may be influenced by:
- Location and neighbourhood demand
- Roads, metro connectivity, and other infrastructure
- Local employment and business activity
- Construction quality and building condition
- Supply of new homes
- Interest rates and borrowing costs
- Legal title and approvals
- Rental demand and affordability
A property in a growing area may appreciate considerably, but buying at an inflated price or choosing a location with weak demand can produce disappointing results.
What affects mutual fund performance?
Mutual fund performance depends on the assets held in the scheme.
Equity fund returns can be affected by company earnings, valuations, economic growth, interest rates, investor sentiment, and global developments. Debt funds can be affected by interest rates, credit quality, and liquidity conditions.
Different funds carry different levels of risk. A diversified portfolio may reduce exposure to a single company, but it cannot remove broader market risk.
Which option offers better returns?
There is no reliable rule that property always outperforms mutual funds, or that mutual funds always outperform property.
For property, calculate the total cost of purchase, financing, maintenance, taxes, vacancy if rented, and selling expenses. For mutual funds, consider the investment amount, fees, taxes, risk, and time horizon.
Compare realistic scenarios rather than relying on the best property appreciation story or the highest historical mutual fund return.
6. Rental Income vs Mutual Fund Investments
Some people buy property primarily to earn rental income. Others prefer investing their savings in mutual funds.
Both approaches can be useful, but they work differently.
Rental income from property
A rental property may generate regular income, but the amount you keep is not necessarily equal to the rent collected.
You may need to pay for maintenance, property tax, repairs, insurance where relevant, society charges, and periods when the property remains vacant. If you have a home loan, rental income may not cover the EMI.
A useful calculation is:
Net rental income = Rental income − property expenses − vacancy losses − other relevant costs
If you are borrowing money to purchase a rental property, also consider loan interest and repayment obligations.
Mutual fund investments
Mutual funds do not automatically produce a fixed monthly income. Your income may come from distributions where applicable or by redeeming units.
Selling units to generate cash reduces the number of units you own and can affect how long your portfolio lasts. Market declines can make withdrawals more difficult, particularly if you need money during a downturn.
Do not assume that a mutual fund’s past annual return is a reliable monthly income rate.
Which is better for regular income?
Rental property may suit people who want to own real estate and are prepared to manage tenants and property expenses. Mutual funds may suit investors who prefer financial assets and want flexibility.
Neither option guarantees a stable income. Your choice should reflect how much cash flow you need, the risks you can tolerate, and how much time you want to spend managing the investment.
7. Which Option Is More Liquid?
Liquidity means how quickly you can turn an investment into cash without a major loss in value.
House or property
Selling a house often requires finding a buyer, negotiating the price, completing documentation, and meeting legal requirements. The process may take weeks or months, and there is no guarantee that you will receive your preferred price.
If you need money urgently, a property can be difficult to sell quickly without accepting a discount.
Mutual funds
Many open-ended mutual funds allow redemptions on business days, with payment made according to the scheme’s settlement rules. However, some schemes have exit loads, restrictions, or lock-in periods, and market conditions can affect the amount you receive.
Equity mutual funds may be particularly unsuitable for money that must be available at a fixed date if you cannot tolerate the risk of a market decline.
For flexibility and ease of accessing money, many open-ended mutual funds have an advantage over direct property ownership. That advantage does not mean that every mutual fund is low-risk or immediately redeemable.
8. Tax Considerations in India
Tax can change the financial outcome of both choices, so it should be considered before making a decision.
Tax considerations when buying or selling property
Depending on the transaction and your circumstances, property ownership may involve stamp duty, registration charges, property tax, taxes on rental income, and capital gains tax when you sell.
Certain tax benefits may be available in specific situations, but eligibility depends on current law, the type of property, how it is used, the loan, and the taxpayer’s circumstances.
Tax considerations for mutual funds
Mutual fund taxation depends on the scheme category, the nature of the income or capital gain, the holding period, and current tax rules.
Equity-oriented funds and debt-oriented funds may have different tax treatments. Tax rates and exemptions can change, so do not rely on an old article or a social media post for your tax calculation.
For official information, consult the Income Tax Department of India and its capital gains information.
For a large property purchase or investment portfolio, consider speaking with a qualified tax professional before acting.
9. Should You Buy a House First or Invest First?
Your priorities matter more than a general rule.
Buying a house may make sense if:
- You need a permanent home for yourself or your family.
- You expect to stay in the same location for many years.
- You can afford the down payment and associated expenses.
- Your EMI leaves enough money for daily living, emergencies, and other goals.
- You have researched the property’s location, legal status, construction quality, and total cost.
- You understand that property prices and rental income are not guaranteed to rise.
Investing in mutual funds may make sense if:
- You already have suitable housing or are comfortable renting.
- You want to invest gradually rather than commit a large sum to one asset.
- You have a long-term investment goal and can tolerate market fluctuations.
- You want more flexibility than direct property ownership generally provides.
- You have an emergency fund and do not need the invested money immediately.
- You understand the risks of the specific mutual fund categories you choose.
Consider investing and buying a home at different stages
You do not always have to choose one option permanently.
Some people invest while saving for a down payment and buy a home later. Others purchase a home for personal use while continuing to invest a portion of their income for retirement or other financial goals.
The right balance depends on your budget, existing assets, debt, family needs, and timeline.
10. A Practical Checklist Before Making Your Decision
Before committing a large amount of money, ask yourself these questions:
- Do I need a house to live in, or am I buying it only for investment?
- How long do I expect to stay in the property?
- Can I comfortably afford the down payment, registration charges, maintenance, and EMI?
- Will I still have an emergency fund after buying the house?
- If I invest instead, where will I live, and how much will rent cost?
- Can I tolerate a significant temporary decline in mutual fund value?
- When will I need the money—within a few years or after a decade or more?
- Am I comparing the total cost of both options fairly?
- Have I considered taxes, inflation, and transaction expenses?
- Have I checked the legal documentation and financial details before making a commitment?
Writing down your answers can help you avoid making a major decision based only on social pressure, fear of missing out, or stories about someone else’s investment success.
11. Common Mistakes to Avoid
Buying property only because everyone else is buying
A house can be a good choice, but buying beyond your budget may create years of financial stress. Choose a property based on affordability, genuine needs, and careful research.
Assuming property prices always increase
Property prices can remain flat or decline. Location, purchase price, construction quality, and demand all matter.
Assuming mutual funds guarantee high returns
Mutual funds are market-linked investments, and returns are not assured. Choose a fund category that fits your goals and ability to bear losses rather than chasing recent performance.
Ignoring rent in the comparison
If you do not buy a house, you may continue paying rent. A fair comparison should account for rent, expected increases, and what you do with the money not spent on a down payment.
Ignoring the cost of a home loan
The purchase price alone does not represent the total cost of owning a financed property. Include interest, fees, maintenance, and other expenses.
Investing money needed soon in risky funds
If you need your money for a house deposit, education, or another near-term goal, a sharp market decline could disrupt your plans. Match your investments to your timeline and risk tolerance.
12. Frequently Asked Questions
Is buying a house better than investing in mutual funds in India?
Neither is automatically better. Buying a house can provide housing security and potential property appreciation, while mutual funds offer flexible ways to invest in financial markets. The right choice depends on your goals, budget, risk tolerance, and time horizon.
Which investment can create more wealth over 20 years?
Both property and mutual funds can create wealth, but neither has a guaranteed outcome. Compare realistic returns after expenses, taxes, loan interest, rent, and other cash flows rather than comparing only headline appreciation or fund returns.
Is an SIP better than buying a house?
An SIP can help you invest gradually and build a financial portfolio. A house provides a place to live or a property that may earn rent. They serve different purposes, so the better choice depends on whether your priority is housing, wealth creation, flexibility, or a combination of these.
Should I buy a house with a home loan or invest the money?
Consider your EMI affordability, loan interest rate, emergency savings, expected time in the home, and investment risk. Taking a large loan while investing in market-linked assets may expose you to both repayment pressure and market volatility. Avoid assuming that investment returns will always exceed the loan cost.
Are mutual funds safer than real estate?
Not necessarily. Different mutual funds have different risks, and equity funds can fluctuate significantly. Property has its own risks, including legal issues, price declines, maintenance expenses, and low liquidity. Safety depends on the specific investment and your financial circumstances.
Can I buy a house and invest in mutual funds at the same time?
Yes, if your income and budget allow it. Some people buy a home and continue investing for retirement or other goals. Make sure that your EMI, household expenses, insurance needs, and emergency savings are manageable before committing to additional investments.
Is rental property a good investment in India?
Rental property may be suitable when the purchase price, expected rent, maintenance expenses, vacancy risk, and local demand make financial sense. Calculate net rental income and consider how much of your wealth would be tied up in the property.
How much should I invest in mutual funds each month?
The appropriate amount depends on your income, essential expenses, emergency fund, debt, financial goals, and risk tolerance. Start with an affordable amount and choose a fund category suited to your time horizon. An SIP amount should not be selected solely because someone else invests that much.
What should I do before investing in mutual funds?
Understand the fund’s objective, risk level, costs, portfolio, and redemption conditions. Use official investor education resources, read the scheme documents, and consider professional advice if you are unsure about suitability.
Should I buy a house before retirement?
That depends on your housing needs, retirement income, location preferences, savings, and other financial commitments. Owning a home can reduce dependence on rental housing, but the purchase should not leave you without enough money for retirement expenses and emergencies.
Conclusion: House or Mutual Funds—Which Is Better?
Buying a house and investing in mutual funds are two different ways to use your money. A house can provide a place to live, long-term stability, and possible appreciation. Mutual funds can offer diversification, flexibility, and potential financial growth without requiring you to purchase a physical asset.
If you need a home, can afford the full cost, and plan to stay in it for many years, buying may be the right choice for your circumstances. If your priority is flexible, long-term investing and you can tolerate market fluctuations, mutual funds may be more suitable.
You do not have to treat the decision as an all-or-nothing choice. A carefully planned combination of housing and financial investments may help meet different goals over time.
Before making a decision, compare total costs, realistic scenarios, risks, taxes, liquidity, and your personal priorities. The best investment is not necessarily the one with the highest potential return—it is the one that fits your financial life and remains manageable when circumstances change.
Disclaimer: This article is for general educational purposes and is not personalised financial, investment, legal, or tax advice. Property prices and mutual fund returns are uncertain. Consult qualified professionals where appropriate before making significant financial decisions.
SHARING IS CARING 💖