The Triple Lock Pension is one of the most important features of the UK’s State Pension system. It determines how the basic and new State Pension are increased each year and is designed to help pension income keep pace with changes in wages and prices.
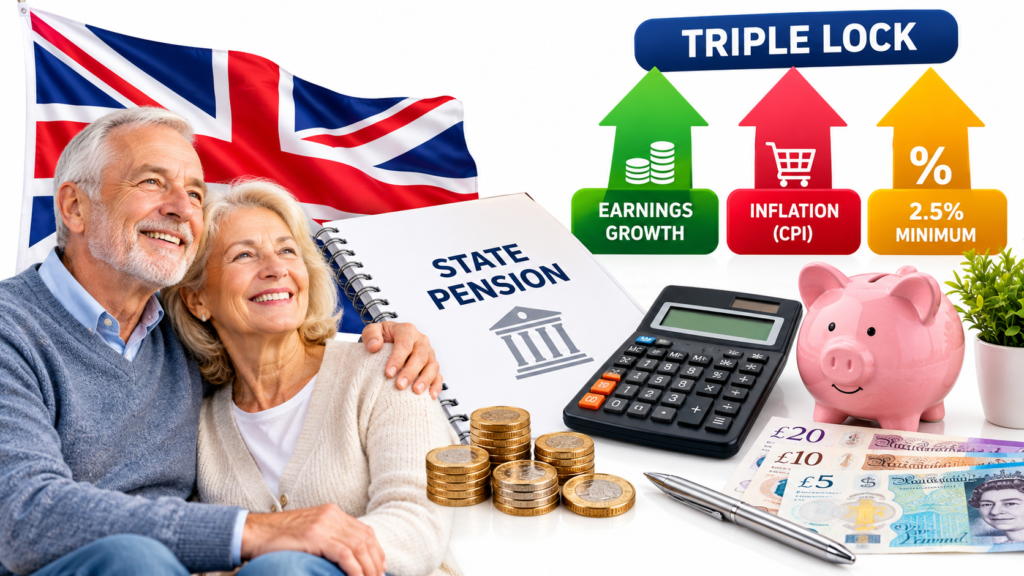
The name “Triple Lock” comes from the three measures used to determine the annual increase. Under the current arrangement, the State Pension is increased by whichever is highest among average earnings growth, inflation measured by the Consumer Prices Index (CPI), or 2.5%.
The policy has attracted considerable public and political discussion because State Pension increases can affect millions of pensioners as well as government spending.
For anyone approaching retirement or already receiving the UK State Pension, understanding how the Triple Lock works can make it easier to understand why pension payments change from one year to the next.
Important: This article is an educational guide to the UK State Pension and Triple Lock. It does not provide personal financial or tax advice. Government rules and payment rates can change, so readers should check the latest information from GOV.UK for their individual circumstances.
What Is the Triple Lock Pension?
The Triple Lock is a mechanism used to determine annual increases to the UK’s basic and new State Pension.
Each year, three measures are considered:
- Average earnings growth
- Inflation measured by CPI
- A minimum increase of 2.5%
The highest applicable figure determines the annual increase.
For example, if the three relevant figures were:
- Earnings growth: 4%
- CPI inflation: 3%
- Minimum: 2.5%
the State Pension increase would be 4%, because earnings growth is the highest of the three.
If inflation were higher than earnings growth, inflation could determine the increase instead.
If both earnings growth and inflation were below 2.5%, the minimum would generally determine the increase.
This is why the system is called a “Triple Lock.”
Why Is It Called a Triple Lock?
The term refers to the three-part protection built into the annual uprating mechanism.
Think of it as three possible measures competing to determine the increase:
Earnings growth → Inflation → 2.5% minimum
The highest figure is used.
This means the State Pension is not automatically increased by the same percentage every year. The percentage can change depending on economic conditions.
For example, in one year earnings might be the highest measure. In another year inflation might be higher. In a year when both are relatively low, the 2.5% minimum may become the applicable figure.
How Does the Triple Lock Work?
The calculation can be understood in a simple way.
Step 1: Measure earnings growth
The government looks at the relevant measure of average earnings growth.
Step 2: Measure inflation
The relevant Consumer Prices Index figure is considered.
Step 3: Compare the figures
The earnings figure, inflation figure, and 2.5% minimum are compared.
Step 4: Select the highest
The highest applicable percentage becomes the basis for the State Pension increase.
Step 5: Apply the increase
The new rate takes effect from April, subject to the detailed rules and legislation governing State Pension uprating.
The Government Actuary’s 2026 report describes the Triple Lock calculation as the highest of annual average earnings growth, September CPI, and 2.5%.
What Is the State Pension Increase for 2026?
For the 2026–27 financial year, the basic and new State Pension increased by 4.8% under the Triple Lock.
The increase took effect in April 2026. The Department for Work and Pensions said the increase was based on average earnings growth because the relevant earnings measure was higher than the inflation and 2.5% components.
The full rate of the new State Pension is £241.30 per week from 2026–27.
The full basic State Pension increased to £184.90 per week from April 2026.
However, not every person receives the full amount. The amount an individual receives depends on factors including their National Insurance record and whether they have circumstances affecting their State Pension entitlement.
How Much Is the New State Pension in 2026–27?
The current full rate of the new State Pension is:
£241.30 per week
That figure applies to the full rate. An individual’s actual payment may be different.
According to GOV.UK, the amount someone receives can depend on their National Insurance record, whether they were contracted out before 2016, and whether they have certain protected amounts from the previous State Pension system.
It is therefore important not to assume that everyone reaching State Pension age automatically receives £241.30 per week.
How Much Is the Basic State Pension in 2026–27?
The full basic State Pension increased from £176.45 to £184.90 per week from April 2026.
The basic State Pension mainly applies to people who reached State Pension age before the new State Pension system was introduced in April 2016.
People reaching State Pension age from 6 April 2016 generally fall under the new State Pension system, although transitional arrangements can make individual situations more complicated.
Who Gets the New State Pension?
The new State Pension applies to people who reach State Pension age under the post-April-2016 system.
The amount depends largely on an individual’s National Insurance record.
For someone whose National Insurance record started after April 2016, 35 qualifying years are generally needed for the full new State Pension, although individual circumstances can affect the calculation.
People with National Insurance records beginning before April 2016 can have more complicated calculations because of the transition from the previous State Pension system.
This is why checking an individual State Pension forecast can be more useful than relying solely on the number of qualifying years.
Does Everyone Receive the Full State Pension?
No.
The “full rate” is the maximum standard amount under the relevant State Pension system. An individual may receive less depending on their National Insurance record and other circumstances.
For example, GOV.UK notes that people who were contracted out before 2016 may have different calculations and may need more than 35 qualifying years to receive the full rate of the new State Pension.
Someone may also have a protected payment from the previous system, which can affect the total amount they receive.
What Are Qualifying National Insurance Years?
A qualifying year is a year that counts toward State Pension entitlement under the National Insurance rules.
Qualifying years can potentially be built through:
- National Insurance contributions from employment
- Self-employed National Insurance contributions where applicable
- National Insurance credits
- Voluntary contributions in certain circumstances
The rules can be complicated, and not every year necessarily counts in the same way.
People approaching retirement can check their National Insurance record and State Pension forecast through the official government service.
Why Does the Triple Lock Matter?
The Triple Lock matters because retirement income can be affected by both inflation and wage growth.
If prices rise significantly, pensioners may face higher costs for everyday necessities.
If wages rise faster than prices, a pension increase linked to earnings can help State Pension payments keep pace with broader wage growth.
The 2.5% minimum provides another layer of protection under the current Triple Lock arrangement.
The objective is therefore to provide a mechanism that adjusts State Pension payments rather than leaving them fixed indefinitely.
Triple Lock and Inflation
Inflation measures how prices for goods and services change over time.
For pensioners, inflation can affect the cost of:
- Food
- Energy
- Housing
- Transport
- Healthcare-related expenses
- Household goods
- Other everyday purchases
If the relevant inflation measure is the highest of the three Triple Lock components, it can determine the State Pension increase for that year.
However, the Triple Lock uses specific official measures and reference periods. It is not simply based on whichever inflation rate a person sees in the news at the time.
Triple Lock and Earnings
The earnings part of the Triple Lock connects State Pension increases with changes in average wages.
This is important because the relationship between pensions and earnings can affect the relative income of retired people compared with working households.
The relevant earnings measure is not simply the salary increase of one individual. It is based on official earnings data used under the State Pension uprating rules.
For the 2026–27 increase, the relevant earnings measure was 4.8%, which was higher than the other Triple Lock components.
What Happens When Inflation Is Higher?
Suppose the relevant figures in a future year were:
- Earnings growth: 3%
- CPI: 5%
- Minimum: 2.5%
Under the basic Triple Lock mechanism, the highest figure would be 5%, so the inflation measure would determine the increase.
This is only an illustration of how the mechanism works and should not be interpreted as a forecast of a future State Pension increase.
What Happens When Earnings Are Higher?
Suppose the figures were:
- Earnings growth: 6%
- CPI: 3%
- Minimum: 2.5%
The earnings figure would be the highest, so the increase would be 6%.
This is similar to what happened for the 2026–27 uprating, when earnings growth of 4.8% was higher than the other relevant components.
What Happens When Both Are Below 2.5%?
Suppose the relevant figures were:
- Earnings growth: 2%
- CPI: 1.8%
- Minimum: 2.5%
The 2.5% minimum would be the highest figure.
Therefore, under the Triple Lock mechanism, the State Pension would be increased by 2.5%.
The minimum is an important part of the policy because it provides a floor when both of the other measures are lower.
Examples of Past Triple Lock Increases
The Triple Lock has produced different annual increases depending on economic conditions.
Official DWP statistics show the following examples:
| April | State Pension increase | Main basis |
|---|---|---|
| 2021 | 2.5% | 2.5% minimum |
| 2022 | 3.1% | CPI |
| 2023 | 10.1% | CPI |
| 2024 | 8.5% | Earnings |
| 2025 | 4.1% | Earnings |
| 2026 | 4.8% | Earnings |
These figures demonstrate that the Triple Lock does not produce the same increase every year.
A special point about 2022
The 2022 increase was unusual because the earnings component was temporarily excluded from the calculation following exceptional earnings distortions during the COVID-19 pandemic.
The State Pension was instead increased by the higher of CPI and 2.5%, resulting in a 3.1% increase.
Is the Triple Lock Guaranteed Forever?
The Triple Lock is a government policy commitment rather than a universal rule that can never change.
Its continuation depends on government policy and legislation.
The Government Actuary’s 2026 report states that the November 2024 Autumn Budget committed to maintaining the Triple Lock for the duration of that Parliament, and the Autumn Budget 2025 restated that commitment.
Future governments or legislation could potentially change the policy.
For this reason, people planning for retirement should not assume that today’s rules will necessarily remain unchanged throughout a retirement that could last several decades.
Does the Triple Lock Apply to All Pension Income?
No.
The Triple Lock applies to the UK’s basic and new State Pension under the relevant rules.
It does not mean that every pension or retirement-income product automatically increases by the same percentage.
Workplace pensions, private pensions, investments, annuities, and other retirement-income arrangements can have completely different rules.
For example, a private pension might have its own terms governing whether and how payments increase.
Therefore, it is important to distinguish between:
State Pension
and
Private or workplace pension income.
Triple Lock vs Workplace Pension
A workplace pension is generally based on pension contributions made during employment and the rules of the particular pension scheme.
The State Pension is separate and is linked to National Insurance and State Pension entitlement.
A person can potentially receive both:
- UK State Pension
- Workplace or occupational pension
- Personal pension
- Other retirement income
The Triple Lock concerns the State Pension component, not the automatic annual increase of all retirement income.
Can You Receive the State Pension While Living Abroad?
It is possible for some people to receive the UK State Pension while living outside the UK, but the rules concerning annual increases can depend on the country where the person lives and other circumstances.
Therefore, someone living abroad should not automatically assume that the same annual uprating arrangements apply to their State Pension.
GOV.UK provides specific information for people receiving or claiming the State Pension while living overseas.
How Can You Check Your State Pension?
One of the most useful steps for someone approaching retirement is to check their official State Pension forecast.
A forecast can help show:
- How much State Pension you may receive
- When you may receive it
- Your National Insurance record
- Whether there are gaps in your record
- Whether additional qualifying years could affect your entitlement
The official GOV.UK service is more reliable for an individual’s circumstances than a general article or online calculator.
Can Voluntary National Insurance Contributions Increase Your State Pension?
In some circumstances, paying voluntary National Insurance contributions may help fill gaps in a person’s record and potentially increase State Pension entitlement.
However, paying voluntary contributions is not automatically beneficial for everyone.
The financial benefit depends on the individual’s existing record, eligibility, future State Pension entitlement, and other circumstances.
Anyone considering voluntary contributions should check their personal State Pension forecast and obtain appropriate guidance before making a payment.
What Is Pension Credit?
Pension Credit is a separate benefit that can provide additional financial support to eligible people who have reached State Pension age and have a lower income.
It should not be confused with the State Pension itself.
The government also uprates certain Pension Credit amounts. For 2026–27, the Standard Minimum Guarantee increased by 4.8%.
Eligibility depends on individual circumstances, including income and other factors.
Someone who receives a State Pension but has a relatively low overall income may therefore want to check whether they could qualify for Pension Credit.
Does the Triple Lock Protect Against the Cost of Living?
The Triple Lock is intended to provide annual protection against changes in earnings and prices, subject to its specific calculation rules.
However, this does not mean that every pensioner’s income will always increase faster than their personal living costs.
Individual households have different spending patterns.
For example, someone facing particularly high housing, energy, healthcare, or other costs may experience a different change in their personal expenses than the national CPI measure.
The Triple Lock is therefore a national uprating mechanism rather than a guarantee that every pensioner’s personal cost of living will be fully covered.
What Are the Main Advantages of the Triple Lock?
The Triple Lock provides a structured mechanism for increasing State Pension payments.
Its main features include:
- A link to earnings growth
- A link to inflation
- A 2.5% minimum under the current mechanism
- Annual increases rather than a permanently fixed payment
- A method that can respond to changing economic conditions
These characteristics explain why the policy is important to people who depend partly or substantially on State Pension income.
What Are the Main Concerns About the Triple Lock?
The policy also creates significant questions about public spending and long-term affordability.
Because the State Pension is paid to millions of people, relatively small percentage changes can have a substantial effect on total government expenditure.
There can also be differences between the growth of pension payments and the economic circumstances of working-age taxpayers.
These are policy questions that governments and policymakers debate, and different analyses can reach different conclusions depending on assumptions about demographics, wages, inflation, taxation, and public spending.
For individual readers, the important point is to distinguish between the mechanics of the Triple Lock and the broader debate about how the UK should fund retirement income.
Triple Lock Pension: Key Facts at a Glance
| Question | Answer |
|---|---|
| What is the Triple Lock? | A mechanism for increasing the basic and new State Pension |
| How many measures are used? | Three |
| What are they? | Earnings, CPI inflation and 2.5% |
| Which figure is used? | The highest applicable figure |
| When is the increase normally applied? | April |
| 2026–27 increase | 4.8% |
| Full new State Pension in 2026–27 | £241.30 per week |
| Full basic State Pension in 2026–27 | £184.90 per week |
| Does everyone receive the full amount? | No |
| Does it apply to private pensions automatically? | No |
The 2026–27 figures above are based on current official government information.
Frequently Asked Questions
What is the Triple Lock Pension?
The Triple Lock is the mechanism used to determine annual increases to the UK’s basic and new State Pension.
Why is it called a Triple Lock?
Because three measures are considered: average earnings growth, CPI inflation, and a 2.5% minimum. The highest applicable measure determines the increase.
How much did the State Pension increase in 2026?
The State Pension increased by 4.8% from April 2026 under the Triple Lock.
What is the full new State Pension in 2026–27?
The full new State Pension rate is £241.30 per week for 2026–27.
What is the full basic State Pension in 2026–27?
The full basic State Pension is £184.90 per week for 2026–27.
Does everyone get £241.30 per week?
No. The £241.30 figure is the full rate of the new State Pension. Individual payments can differ depending on National Insurance records and other circumstances.
Does the Triple Lock apply to private pensions?
No. The Triple Lock relates to the UK’s basic and new State Pension. Private and workplace pensions operate under their own rules.
Can the Triple Lock change in the future?
Yes. Government policy and legislation can change. People planning for long-term retirement should check the latest official rules.
How can I find out how much State Pension I may receive?
You can use the official GOV.UK State Pension forecast service to check your individual position and National Insurance record.
Is the Triple Lock the same as Pension Credit?
No. Pension Credit is a separate benefit designed to provide additional support to eligible people with lower income.
Final Thoughts
The Triple Lock Pension is a mechanism that plays a major role in determining how the UK’s State Pension changes from year to year.
Its basic formula is straightforward: compare earnings growth, CPI inflation, and the 2.5% minimum, then use the highest applicable figure.
The 2026–27 increase was 4.8%, bringing the full new State Pension to £241.30 per week and the full basic State Pension to £184.90 per week.
However, the amount any individual receives depends on their own circumstances, particularly their National Insurance record and which State Pension system applies to them.
For anyone planning retirement, the most useful approach is to check their personal State Pension forecast rather than relying on the headline full rate.
The Triple Lock is also only one part of retirement planning. Workplace pensions, personal pensions, savings, investments, taxes, housing costs, and other sources of income can all affect a person’s financial position in retirement.
Disclaimer: This article is for general educational and informational purposes only. It is not financial, pension, tax, or legal advice. UK pension rules and rates can change, and individual circumstances differ. Always check the latest information on GOV.UK or consult a suitably qualified professional before making financial decisions.
SHARING IS CARING 💖